
Car Finance PCP Calculator & Balloon GFV Tool
Calculate monthly repayments and interest with our car finance pcp calculator. Evaluate balloon payments, GFV equity, and voluntary termination terms.
Free · runs in your browser · nothing is uploaded
Recent
Your last 10 settings, saved only in this browser. Nothing is uploaded.
The Motwatch car finance PCP calculator provides UK car buyers and personal lease shoppers with transparent mathematical modeling for Personal Contract Purchase (PCP) agreements. PCP is a common way to finance new and used cars in Great Britain, offering lower monthly repayments than conventional hire purchase by deferring a substantial capital sum until the end of the contract.
Our calculator works from the price, deposit, term, APR and GMFV you type in (it converts the APR, an annual rate including compounding, to a monthly rate). It breaks down vehicle depreciation repayments, deposit contributions, and compounding interest charges applied across both the loan principal and the Guaranteed Minimum Future Value (GMFV). Evaluate realistic payment schedules, voluntary termination thresholds, and total cost of ownership before signing dealership finance agreements, so you can check a dealer’s quote before signing.
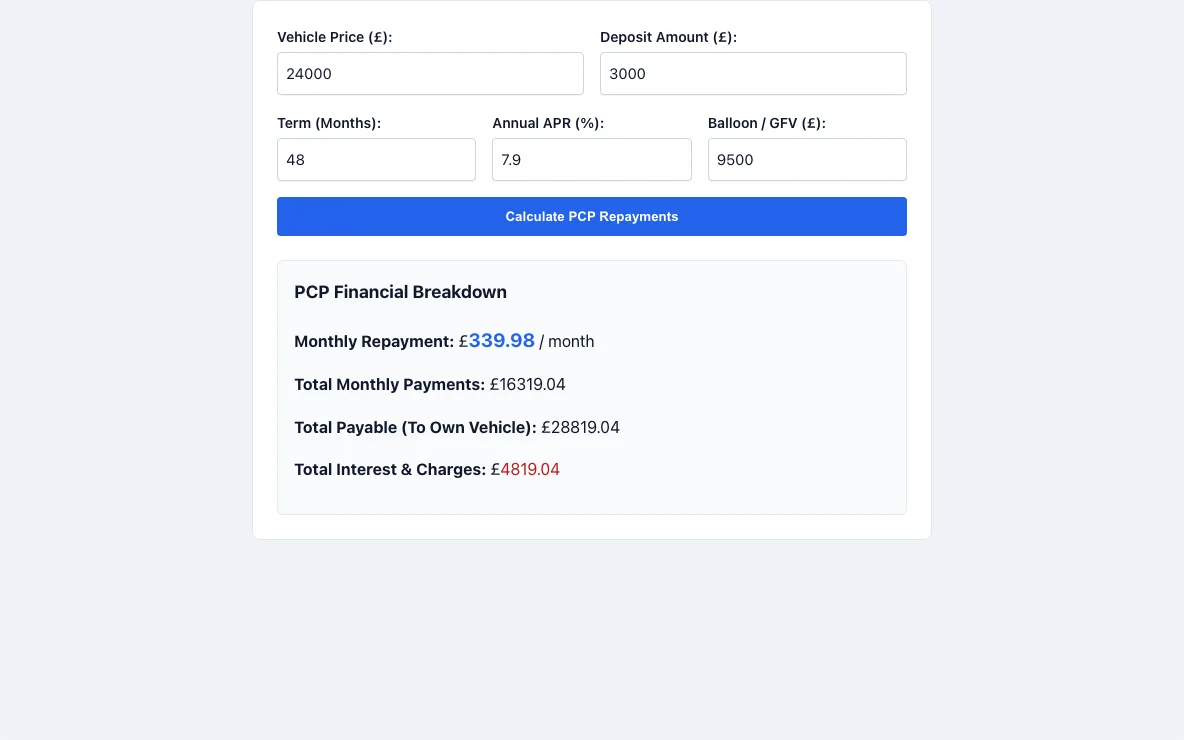
How to use the car finance pcp calculator & balloon gfv tool
- Step 1: Enter the total vehicle on-the-road purchase price quoted by the dealership or commercial vehicle retail specialist.
- Step 2: Input your cash deposit combined with any promotional dealership finance deposit contributions or part-exchange equity allowances.
- Step 3: Select your contract duration in months, typically chosen as 36, 48, or 60 monthly cycles depending on mileage projections.
- Step 4: Enter the quoted annual percentage rate (APR) representing the true annual cost of consumer credit and financing charges.
- Step 5: Input the Guaranteed Minimum Future Value (GMFV) or optional final balloon repayment figure quoted by the automotive lender.
- Step 6: The results update as you type; the Calculate PCP payments button does the same.
- Step 7: Review the estimated monthly repayment figure required over the active vehicle agreement duration to plan household budgets.
- Step 8: Examine the total cumulative sum of regular monthly instalments paid throughout the entire contract lifecycle.
- Step 9: Inspect the total amount payable if you choose to settle the optional balloon payment and acquire outright vehicle ownership.
- Step 10: Check total interest and finance charges incurred compared against outright cash vehicle purchases or personal bank borrowing.
- Step 11: Compare PCP repayment amounts against equivalent Hire Purchase terms to evaluate ownership equity and voluntary termination milestones.
How PCP finance works
Voluntary Termination Under the Consumer Credit Act 1974
Under Section 99 of the Consumer Credit Act 1974, motorists entering regulated hire purchase and conditional sale agreements retain the statutory right to voluntary termination. Once you have paid at least 50% of the total amount payable (including interest and the balloon payment), you can return the car to the finance company without further financial liability, providing valuable protection against negative equity if used car market valuations plunge unexpectedly.
Deconstructing Depreciation Repayment vs Balloon Interest Drag
Many consumers mistakenly believe interest is only charged on the money paid off monthly. In reality, the lender finances the entire purchase price minus deposit, meaning you pay annual interest on the large balloon payment throughout the entire 36 or 48-month duration. This creates significant interest drag, making PCP substantially more expensive than HP if you intend to keep the vehicle permanently rather than handing it back to the dealer.
The Three Contract-End Options Under UK PCP Agreements
At the conclusion of a PCP contract, motorists have three distinct options: pay the predetermined balloon payment (GMFV) to purchase the car outright, return the vehicle to the lender with nothing further to pay subject to condition, or trade the vehicle in where any positive market equity above the GMFV is credited as deposit toward your next car. Understanding this triad allows drivers to negotiate favorable initial terms and avoid surprise end-of-contract costs.
Excess Mileage Surcharges and BVRLA Return Standards
If you choose to hand the car back, lenders charge for every mile over the agreed limit at the pence-per-mile rate set in your agreement. Furthermore, any cosmetic or mechanical damage exceeding the British Vehicle Rental and Leasing Association (BVRLA) fair wear and tear guide will trigger itemized recharge invoices, requiring meticulous vehicle inspection before the collection driver arrives.
Frequently asked questions
How does a Personal Contract Purchase agreement function?
A PCP agreement lets you finance the vehicle depreciation between initial purchase price and Guaranteed Future Value (GFV), keeping monthly repayments lower than traditional hire purchase loans.
Why is interest charged on the balloon payment throughout the PCP term?
Because the GFV balloon amount is deferred until the final month rather than paid down during the contract, the lender charges annual interest on that full principal balance across all contract months.
What happens at the end of a PCP finance term?
At contract end, you have three legal choices: pay the optional balloon payment to own the car, hand the vehicle back with nothing more to pay, or part-exchange towards another model.
What is the 50% Voluntary Termination rule under UK credit law?
Under Section 99 of the Consumer Credit Act 1974, you can voluntarily terminate a PCP contract and return the vehicle without further liability once you have paid at least 50% of the total amount payable.
Can I settle my PCP finance agreement early?
Yes, UK consumer regulations require lenders to provide a statutory early settlement quote valid for 28 days, with a rebate of future interest worked out under the Consumer Credit (Early Settlement) Regulations 2004.
Is the Guaranteed Minimum Future Value negotiable?
Not directly. The lender sets the GMFV from its own residual-value forecasts, and it changes with the term, deposit and annual mileage you choose, so changing those changes the GMFV.
Related tools
- Car Finance HP Calculator & Hire Purchase Tool
- Car Insurance Group Checker: Groups 1–50 Explained
- Car Scrappage Scheme Calculator & Scrap Value Estimator
- Car Warranty Expiry Checker & End Date Calculator
- EV Charging Cost Calculator & Home vs Public Rates
- Electric Vehicle Charging Time Calculator & Speed Tool
- EV Battery Degradation Calculator & SoH Health Tool
- Speedometer Accuracy Calculator: True Speed & Tyre Size
See all Car Running Cost and Finance Tools.